Market Report ·
OCT 5 monday report - dr ayush
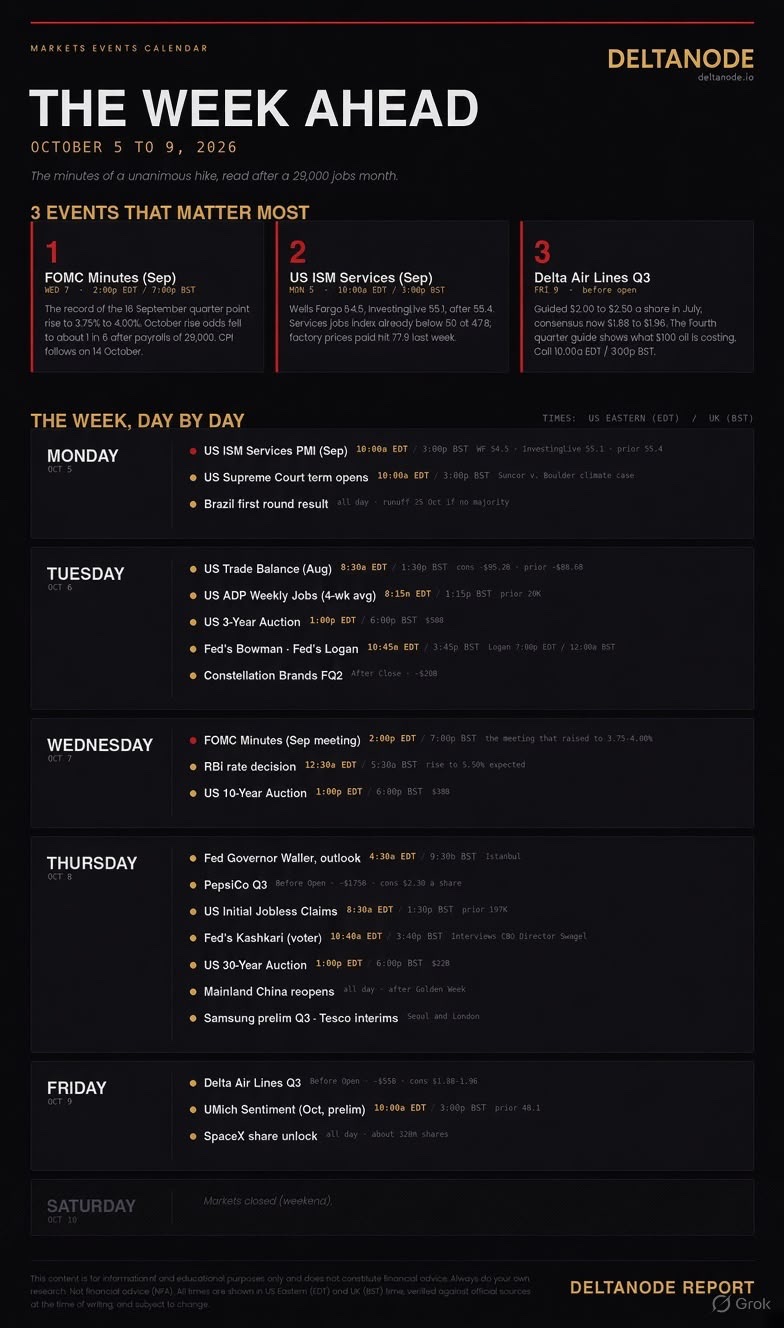
📊 THIS WEEK — MACRO & MARKETS
🔴 HIGH IMPACT
• 🇺🇸 US ISM Services PMI — Monday 10:00 AM ET / 3:00 PM BST
• 🇺🇸 FOMC Minutes (September Meeting) — Wednesday 2:00 PM ET / 7:00 PM BST → Key focus: Fed members’ views on rates, inflation and the next move.
• 🇺🇸 US 10Y & 30Y Treasury Auctions — Wed/Thu 1:00 PM ET / 6:00 PM BST → Watch yields and demand; weak auctions could pressure risk assets.
🟠 OTHER IMPORTANT EVENTS
• 🇺🇸 Initial Jobless Claims — Thursday 8:30 AM ET / 1:30 PM BST
• 🇺🇸 Fed Governor Christopher Waller Speaks — Thursday 4:30 AM ET / 9:30 AM BST
• 🇺🇸 University of Michigan Sentiment — Friday 10:00 AM ET / 3:00 PM BST
• ✈️ Delta Air Lines Q3 Earnings — Friday, pre-market
• 🥤 PepsiCo Q3 Earnings — Thursday, pre-market
• 🚀 SpaceX Share Unlock — Friday, all day
━━━━━━━━━━━━━━
📌 LAST WEEK — WHAT MATTERED
🇺🇸 US JOBS NFP came in at just 29K vs 90K expected. Unemployment rose 4.1% → 4.2%, while wage growth was only +0.1% MoM.
July & August were revised down by a combined 60K.
➡️ The labor market is clearly showing signs of cooling. ➡️ October Fed hike odds fell to around 17% on CME FedWatch.
📉 US PCE Core PCE rose 0.2% MoM / 3.0% YoY, below expectations.
But spending remained strong: +0.9% nominal / +0.6% real.
➡️ Inflation is cooling, but consumers are still spending.
💾 MICRON Revenue: $54.23B vs ~$51.1B expected Gross margin: 86.8% Next-quarter guidance: $60–63B
Management expects memory supply to become much tighter in 2027–28.
🇪🇺 EUROZONE INFLATION Headline inflation jumped to 3.8% vs 3.7% expected, with energy up 18.8%.
Core inflation: 2.5% vs 2.4%.
➡️ ECB rate-cut expectations remain complicated, with markets still pricing the possibility of another hike later this year.
━━━━━━━━━━━━━━
🌍 THE BIGGER PICTURE
🇦🇺 Australia raised rates to 4.60%, its fourth hike this year.
🇺🇸 US manufacturing prices paid jumped to 77.9, showing renewed inflation pressure.
🛢️ OPEC+ kept November output targets unchanged. Brent settled around $102.25.
🚗 Tesla delivered 486,532 vehicles, beating expectations of 461,974. Q3 results: 21 October after close.
━━━━━━━━━━━━━━
🎯 WHAT WE WATCH THIS WEEK
The biggest question is the Fed + inflation + growth combination.
Jobs are weakening and PCE was softer, but oil and manufacturing prices are pushing inflation expectations higher.
The FOMC Minutes + Treasury auctions + ISM Services + Fed speakers should give us more clues about the next Fed move.
And remember: September CPI is coming on 14 October.
Let’s focus on the data, liquidity, yields and macro direction rather than trying to predict every candle. 📈📉