Market Report ·
MARKET WATCH 📅 19–23 October 2026
⚠️ Inflation remains elevated, while underlying consumer spending signals are less convincing.
🌐 DELTANODE | WEEKLY MACRO & MARKET WATCH 📅 19–23 October 2026
📊 LAST WEEK: WHAT MATTERED
🇺🇸 US Inflation — CPI & PPI • September CPI rose 0.6% MoM and 3.7% YoY, with core inflation accelerating to 2.6% YoY. • PPI surged 1.3% MoM and 6.3% YoY, with energy accounting for over 80% of the monthly increase. • Retail sales rose 0.8%, but the GDP-linked control group increased just 0.1%.
⚠️ Inflation remains elevated, while underlying consumer spending signals are less convincing.
🏦 Fed Rate Outlook Fed rate-hike expectations for October briefly approached 50% before retreating to around 17% by Friday. December expectations remained elevated.
The next major catalyst is the 28 October Fed decision, with earnings and Friday's US Flash PMIs providing important signals beforehand.
📉 US Equities • S&P 500: −1.95% weekly • Nasdaq: −4.48% weekly, its worst week since June • Semiconductor stocks remained under pressure despite strong TSMC earnings.
🖥️ TSMC Q3 Record net income reached approximately $23.6B, up 69% YoY, while Q4 revenue guidance exceeded consensus. However, shares still sold off, highlighting how elevated expectations and positioning can outweigh strong fundamentals.
🏦 Big Banks JPMorgan missed earnings expectations, Goldman Sachs benefited from strong equities trading, and Bank of America faced a $1.2B Treasury penalty. Citi also signalled a potential decline in Q4 markets revenue.
🛢️ Oil & Geopolitical Risk Brent settled at $109.86, following Iranian claims that two tankers struck mines in the Strait of Hormuz. The claims remain independently unconfirmed.
Energy prices are a key variable for inflation, Treasury yields, Fed expectations and broader risk appetite.
━━━━━━━━━━━━━━
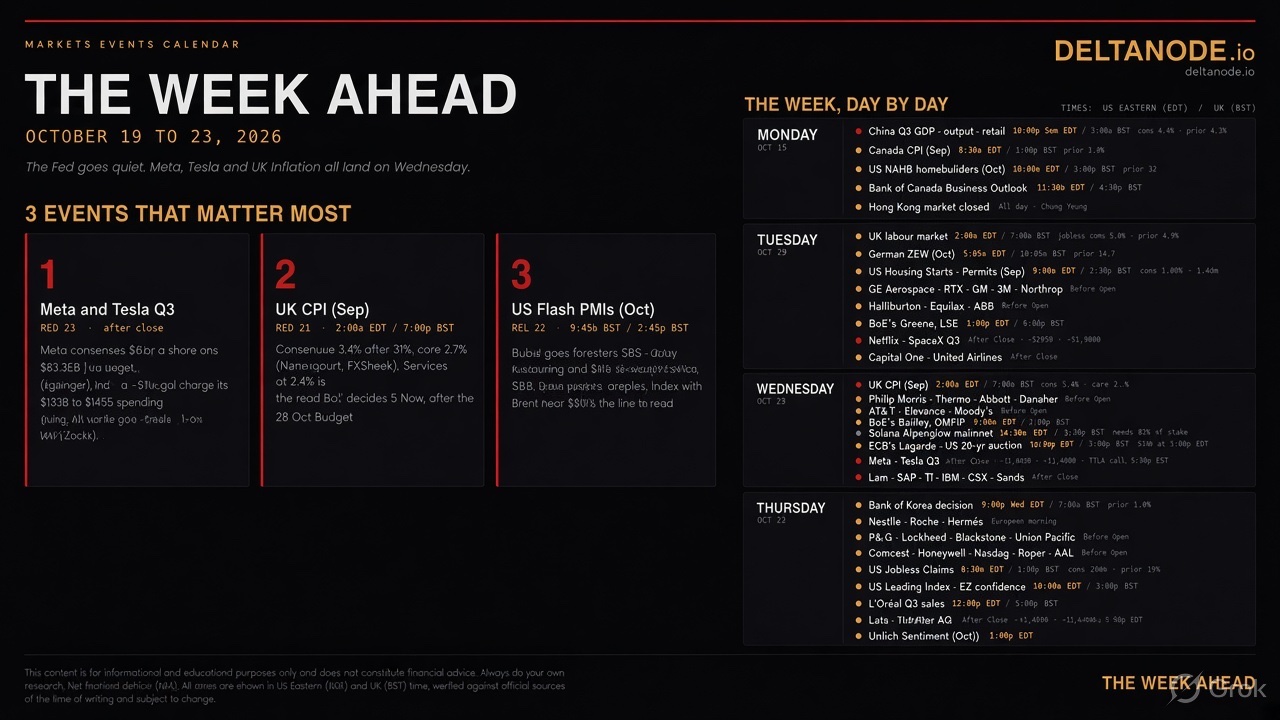
📅 WEEK AHEAD | KEY CATALYSTS
🔴 MONDAY, 19 OCT 🇨🇳 China Q3 GDP — 10:00 PM ET
🔴 TUESDAY, 20 OCT 🎬 Netflix Q3 results — After Close 🚀 SpaceX results — timing subject to confirmation ✈️ GE Aerospace, RTX, GM & 3M — Before Open 🇬🇧 UK Labour Market — 2:00 AM ET
🔴 WEDNESDAY, 21 OCT 💻 Meta, Tesla, IBM, Texas Instruments, Lam Research & SAP — After Close 🇬🇧 UK CPI — 2:00 AM ET 🟠 Solana Alpenglow upgrade — scheduled for 10:50 AM ET; timing subject to confirmation
🟠 THURSDAY, 22 OCT 🥤 Procter & Gamble 🛡️ Lockheed Martin 🏦 Blackstone 🚆 Union Pacific All scheduled before the US market open.
🔴 FRIDAY, 23 OCT 🇺🇸 US Flash PMIs — 9:45 AM ET
Times are as listed in the supplied schedule; verify individual company announcements and event timings before trading.
━━━━━━━━━━━━━━
🎯 DELTANODE | WHAT TO WATCH
1️⃣ Inflation vs Fed: Do energy-driven price pressures translate into tighter monetary expectations?
2️⃣ Earnings vs Valuations: Can mega-cap technology results stabilise the Nasdaq and semiconductor sector?
3️⃣ Oil & Hormuz: Any confirmed disruption could amplify inflation concerns and volatility.
4️⃣ China GDP: Watch for signs of economic acceleration or continued weakness in global demand.
5️⃣ Crypto: Monitor BTC price structure, spot vs perpetual flows, open interest, funding and ETF flows. The Solana upgrade is a separate ecosystem catalyst, not automatically a directional signal for the broader market.
⚠️ BOTTOM LINE
Markets enter the week facing a difficult combination of elevated inflation, geopolitical risk, weakening equity momentum and major earnings catalysts.
Strong results alone may not be enough if valuations are stretched or guidance disappoints. Equally, an inflation shock does not automatically guarantee another rate hike.
Focus on confirmed data, market reaction and positioning. No assumptions, no forced trades. Let the evidence lead.
Δ Σ Φ | DELTANODE Market intelligence, not financial advice.