Market Report ·
🌍 DELTANODE | WEEKLY MACRO REPORT 📅 26–30 October 2026
Markets face a critical week with the Fed decision, US GDP and PCE inflation, and earnings from Microsoft, Alphabet and Amazon. Brent is at $116.72, while US 10Y yields approach 5%. Rising inflation and AI spending remain key risks. Watch the dollar, yields, liquidity and Bitcoin flows for market direction. 📊
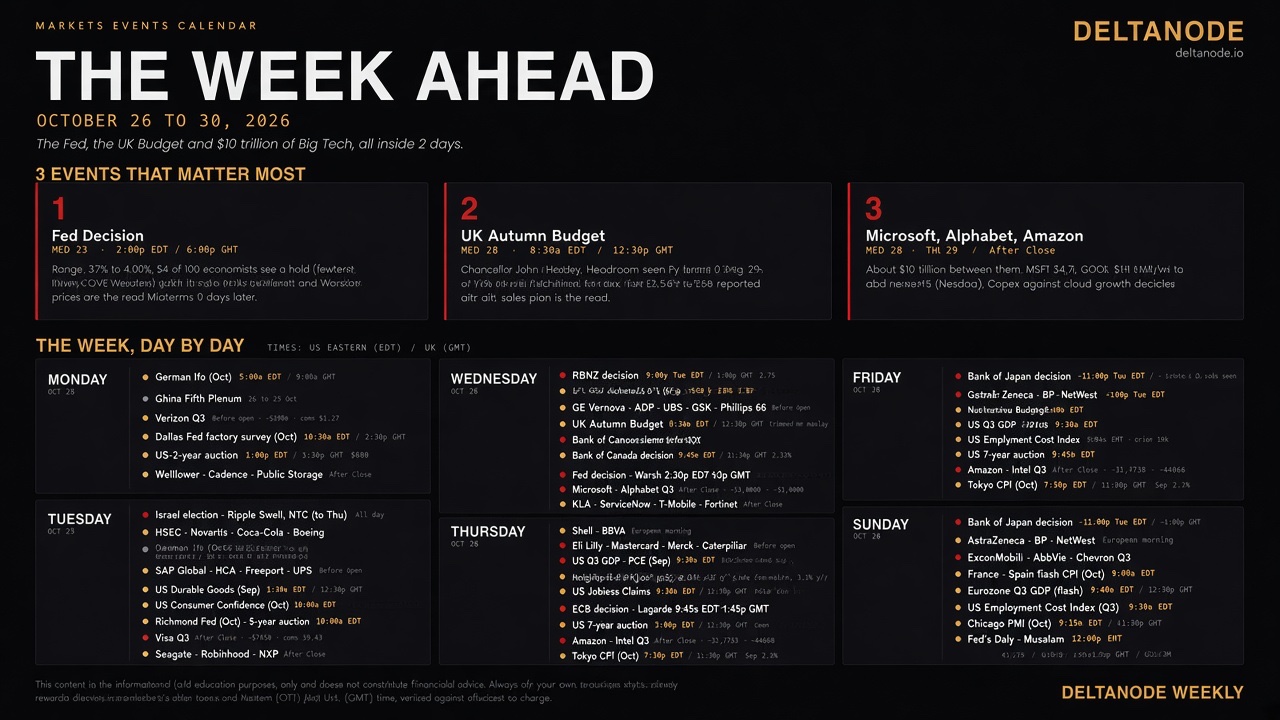
The Fed, Big Tech Earnings & Inflation: A Critical Week for Markets
Markets enter one of the most important weeks of October with inflation pressures rising, oil prices surging, bond yields approaching 5%, and investors waiting for the Federal Reserve's next move. Meanwhile, Microsoft, Alphabet and Amazon will provide a crucial test of whether massive AI investments are translating into sustainable growth.
━━━━━━━━━━━━━━
📊 1. LAST WEEK: WHAT MOVED MARKETS?
🔹 Meta & Tesla: Two Different Spending Strategies
• Meta reported $64.6B in revenue, up 26% year over year, but capital expenditure of $34.91B exceeded operating cash flow of $32.79B. • Meta narrowed its 2026 spending outlook to $135B–$145B, without providing a 2027 forecast. Shares fell 6.98% to $648.85 on Thursday. • Tesla beat earnings expectations, reporting $0.48 per share against $0.43 expected, while cutting its capital spending budget to approximately $20B from more than $25B.
DeltaNode Take: AI spending remains a major market theme, but investors increasingly want evidence of returns on capital, not just revenue growth. Strong earnings may not be enough if spending continues to outpace cash generation.
🔹 UK Inflation Accelerates
• September CPI: 3.5%, above the 3.4% forecast and up from 3.1% in August. • Core inflation rose to 2.8% from 2.6%. • Services inflation increased to 3.7% from 3.4%.
The Bank of England faces a difficult decision on 5 November, particularly with the UK Budget arriving first.
🔹 US Business Activity Remains Strong, but Inflation Is the Concern
• Manufacturing PMI: 56.0 vs. 55.5 expected. • Services PMI: 57.9 vs. 58.0 expected. • Composite PMI: 57.6, down from 58.4. • The output prices index climbed to 59.8, its highest reading since August 2022.
The combination of resilient activity and rising prices complicates the case for aggressive monetary easing.
━━━━━━━━━━━━━━
📉 2. MARKET POSITIONING
🇺🇸 US Equities • S&P 500: 7,623.68, down 0.47% for the week. • Nasdaq: down 0.71%, marking a second consecutive weekly decline.
The market is entering a major earnings and macroeconomic window. AI-related guidance and the Fed's messaging could determine whether technology stocks regain momentum or face further pressure.
🛢️ Oil • Brent crude settled at $116.72 per barrel on Friday, up $3.55.
Elevated oil prices add to inflation risks and could delay interest-rate cuts. Any further supply disruption could intensify pressure on both consumers and central banks.
📈 US Treasury Yields • The 10-year Treasury yield ended the week at 4.99%.
Yields near 5% create a tougher environment for long-duration growth stocks, speculative assets and other rate-sensitive investments.
The central macro conflict: Economic activity remains resilient, but persistent inflation, expensive energy and elevated yields limit the room for central banks to ease policy.
━━━━━━━━━━━━━━
🚨 3. WEEK AHEAD: MAJOR CATALYSTS
🔴 WEDNESDAY, 28 OCTOBER
🏦 Federal Reserve Interest-Rate Decision • 2:00 PM ET / 6:00 PM GMT • Chair Kevin Warsh's press conference follows at 2:30 PM ET / 6:30 PM GMT.
Markets are focused on the decision, the inflation outlook and signals about the December meeting. A hold may already be largely priced in, making the Fed's forward guidance especially important.
🇨🇦 Bank of Canada Decision • 9:45 AM ET / 1:45 PM GMT.
💻 Microsoft & Alphabet Earnings • After the US market close.
Watch cloud growth, AI monetization, capital expenditure, margins and forward guidance.
🔴 THURSDAY, 29 OCTOBER
🇺🇸 US Q3 GDP & September PCE Inflation • 8:30 AM ET / 12:30 PM GMT.
GDP will provide a broader picture of economic growth, while PCE and core PCE inflation will help assess underlying price pressures.
🛒 Amazon Earnings • After the US market close.
AWS growth, AI infrastructure spending, operating margins and forward guidance will be key.
🇪🇺 European Central Bank Decision • 9:15 AM ET / 1:15 PM GMT.
🇯🇵 Bank of Japan Decision • Thursday night ET / Friday morning GMT.
🇺🇸 FRIDAY, 30 OCTOBER
Keep an eye on the latest corporate earnings, energy-market developments and Treasury yields as investors digest the week's central-bank decisions and economic data.
━━━━━━━━━━━━━━
🔬 4. WHAT DELTANODE IS WATCHING
1️⃣ Inflation vs. Monetary Policy: Stronger price pressures could force markets to reassess expectations for future rate cuts.
2️⃣ Oil vs. Risk Assets: Sustained elevated oil prices could pressure inflation expectations, consumer spending and equity valuations.
3️⃣ Yields vs. Technology Stocks: A move higher in Treasury yields could challenge expensive growth-stock valuations, even when earnings beat expectations.
4️⃣ AI Spending vs. Cash Flow: Microsoft, Alphabet and Amazon must demonstrate that AI investment can generate durable revenue and profits.
5️⃣ Liquidity & Crypto: Watch the dollar, Treasury yields, Bitcoin spot demand, ETF flows, open interest and CVD for confirmation. Do not assume that a Fed decision automatically means a bullish move for Bitcoin.
━━━━━━━━━━━━━━
🧠 DELTANODE CONCLUSION
This is a high-event-risk week. Markets are balancing resilient economic activity against rising inflation pressures, elevated energy prices and substantial AI spending.
A dovish Fed message combined with cooling inflation and strong earnings could support risk assets. Conversely, hawkish guidance, sticky PCE inflation or weaker technology-sector outlooks could put renewed pressure on equities and crypto.
The key is not simply whether the Fed cuts or holds. It is whether incoming data supports easier financial conditions or forces markets to price in tighter policy for longer.
⚠️ Trading principle: Let the data, liquidity and price action confirm the direction. Avoid taking positions solely on event expectations, and be cautious around major announcements when volatility and liquidation risk can rise sharply.
DeltaNode | Understand the market. Control the risk. Follow the evidence.